Most couples taking a joint home loan get the tax pitch from their bank agent, the numbers sound great, and they sign without asking the one question that actually determines whether those numbers apply to them: is the property registered in both names, or just one? That single detail — not the loan itself — decides whether you’re getting double the tax benefit or accidentally leaving thousands on the table every year.
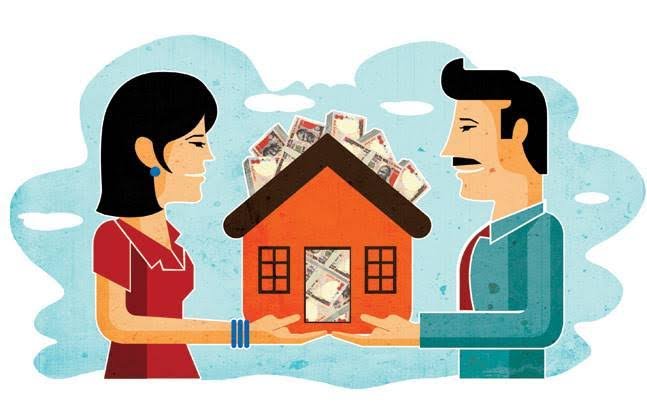
The Mistake That Costs Couples the Most
A joint loan and joint ownership sound like the same thing. They’re legally not, and the Income Tax Act cares about the difference enormously.
- Tax deductions require you to be BOTH a co-applicant on the loan AND a registered co-owner on the property’s sale deed
- Paying EMI without your name on the sale deed earns you zero deduction, regardless of how much you’re contributing
- This mismatch happens constantly when couples add both names to the loan application for eligibility purposes but register the flat in just one name for simplicity
What’s Actually on Offer When You Get the Structure Right
Assuming both boxes are ticked — co-applicant and co-owner — here’s what each person can independently claim under the old tax regime:
- Section 24(b): up to ₹2,00,000 per person annually on home loan interest for a self-occupied property
- Section 80C: up to ₹1,50,000 per person annually on principal repayment (shared limit with other 80C investments like PPF or ELSS)
- Section 80EE/80EEA: an additional ₹50,000 for eligible first-time buyers meeting specific property value and loan amount conditions
Add it up correctly and a couple can claim combined deductions approaching ₹7 lakh a year — a genuinely different tax outcome than a single applicant claiming alone.
Your Deduction Follows Your Ownership Percentage, Not Your Salary
This surprises people who assume deductions simply split 50-50 between spouses.
- Your claimable deduction is proportional to your actual ownership share as listed on the sale deed
- A 70:30 ownership split means deductions follow that same 70:30 ratio — regardless of who earns more or who’s transferring more money toward the EMI each month
- If a co-borrower contributes nothing toward EMI, the full interest deduction can be claimed by whoever is actually paying it
The Regime Question That Makes All of This Irrelevant for Some Couples
Before getting excited about the numbers above, this needs checking first.
- The New Tax Regime, now the default for most taxpayers, does not allow deductions under Section 80C or 24(b) for a self-occupied property
- These benefits exist only under the Old Tax Regime
- As a rough guide, the Old Regime tends to win once your combined eligible deductions cross roughly ₹4 lakh — but this genuinely needs calculating with your actual numbers, not assumed
The Financial Risk Everyone Skips Past
Couples get so focused on maximizing deductions that the actual lending risk barely gets discussed.
- If one co-applicant dies or becomes unable to pay, the bank pursues the surviving co-applicant for the ENTIRE outstanding loan — not their proportional share
- A joint home loan protection insurance policy genuinely closes this gap, and the premium is modest relative to what it protects against
- Both applicants’ credit scores are tied to the same loan — a missed payment damages both credit histories, not just whoever forgot
What the Tax Department Can Actually Ask You to Prove
This matters if your return is ever scrutinized, which happens more often with joint claims than solo ones.
- Both co-owners must show they’re genuinely contributing toward EMI in proportion to what they’re claiming
- Keep clean records — linked bank accounts, or a documented transfer trail if one spouse pays the bank directly and the other reimburses them
- Vague or undocumented contribution splits are exactly what triggers follow-up questions during assessment
A Genuine Side Benefit Worth Asking About
Beyond the tax conversation entirely, several Indian lenders offer a marginally lower interest rate when a woman is included as co-applicant and co-owner. This isn’t universal across every bank, so it’s worth asking your specific lender directly rather than assuming it’s automatically baked into your quoted rate.
Frequently Asked Questions
Q1. We’re both paying EMI but only my husband’s name is on the property — can I fix this now?
Yes, through formal re-registration adding you as co-owner, though this involves fresh stamp duty and registration costs in most states. Calculate whether the ongoing annual tax savings genuinely justify that one-time expense before proceeding.
Q2. Do we need to be married to both claim deductions on a joint home loan?
No — the tax benefit applies to any co-owners who are also co-borrowers contributing to EMI, which is exactly why siblings or parent-child pairs sometimes structure joint loans the same way as spouses do.
Q3. Is it worth switching to the Old Tax Regime purely to access these home loan deductions?
Only if your actual numbers support it — run both regime calculations with your real income and deduction total rather than assuming the Old Regime automatically wins just because home loan benefits exist there.
Q4. What happens to our home loan tax benefits if we later rent out the property instead of living in it?
The rules change — a rented-out property falls under different deduction limits than a self-occupied one, particularly for interest under Section 24(b), so it’s worth checking updated limits with a tax advisor before assuming your current deduction structure continues unchanged.